 Facts are friends
The moat
Thomson Reuters and RELX built category-defining businesses on curated legal data.
For decades, Westlaw and LexisNexis have been the twin pillars of legal research - comprehensive, authoritative and verified. They invested heavily in collecting, collating and indexing core legal data in as near real time as possible. From High Court to County Court materials, HMRC to professional practice notes, they have systems in place to capture them all. For years the data moat has appeared impregnable. Simply put, lawyers could not practise without them. Law firms may have tried to negotiate subscription terms, but both sides knew that they needed the data flow and the subscriptions were paid for without question.
The model was simple, sticky and enormously profitable. They seemed unassailable and guaranteed to maintain income at those levels for many decades to come. That last, the guaranteed maintained income, is now under threat. In fact, I believe it is already changing.
That moat remains real.
But the battleground - at least in relation to commercial and corporate law - is shifting in ways that the conventional disruption narrative does not make clear.
The threat to TR and RELX is not primarily that their product is being challenged by something better or cheaper. It is that the customer channel through which all their revenue flows is under the existential structural pressure from three directions simultaneously - compression, fragmentation and migration
This is not a eulogy. It is a siren call.
This is not merely a legal technology debate. It has already reached the capital markets. Investors have questioned whether AI tools will undercut LexisNexis, sending RELX shares down significantly before the company pushed back - pointing to the scale of its proprietary corpus and Shepard's citation infrastructure as its defence. RELX’s counter-argument should be taken seriously. It says its advantage lies in proprietary, refined data, decades of curation and trusted workflow tools that general models cannot simply replicate. That answer is not wrong. It is incomplete. The issue is not whether the moat exists. The issue is whether the moat remains positioned where the customer journey still runs: the moat is real, but the market is already questioning whether it still sits in the right place.
The customer channel problem
TR and RELX provide information which is, currently, necessary to allow businesses to implement sustainable, risk-reduced business relationships. They do not typically sell directly to the businesses that benefit from their information. They sell to lawyers - overwhelmingly in law firms, but increasingly to in-house lawyers, too.
Legal professionals are the customers. The lawyers open the session, extract the value and pay the subscription. Their pricing models are closely correlated with lawyer headcount and usage intensity within firms.
Thomson Reuters' Legal Professionals segment generated $2.868bn in 2025. RELX's LexisNexis Legal and Professional division generated £1.806bn (about one-fifth of RELX’s group total revenues). These are not niche tools. They are core professional infrastructure businesses, sitting inside much larger information groups - and their revenue is structurally coupled to lawyer headcount.
The scale of that coupling is less visible than it should be. Within most large law firms, spend with TR and RELX is fragmented across library services, knowledge management, innovation functions and IT procurement. Few firms have ever consolidated those figures into a single line. The senior leadership of the law firm - the people who will decide how to respond to AI disruption - frequently do not know what they spend with either company. That invisibility cuts both ways. It means the disruption is harder to anticipate from inside the firm. And it means the impact will feel more sudden when the consolidated numbers finally surface.
That relationship has been so stable for so long that it has assumed constant state rather than a strategic variable. Those at the top of these businesses need to question that assumption.
AI targets precisely the layers of legal work that historically drove headcount growth. As that headcount reduces, the subscription base reduces with it - not because Westlaw or LexisNexis becomes less valuable, but because the law firm is no longer the dominant distribution channel it once was. New buyers are emerging: in-house teams, compliance functions, AI-native platforms. But they do not yet replace the revenue density of the law firm pyramid at scale.
This is the consumption paradox applied to legal data. When a client drafts her own NDA using an AI tool embedded in Word, she does not find a cheaper lawyer or a cheaper research platform. She finds that she does not need either.
What happens to demand is not simple substitution. Some demand migrates to cheaper providers. Some internalises as clients self-serve. Some shifts upstream toward governance, system design and edge cases where human judgement remains essential. And some disappears altogether - at the precise point where the instruction would previously have been created.
The shift from seat licence to consumption-based pricing compounds this pressure. As agentic workflows replace individual lawyer research sessions, the revenue model changes shape even where the subscription relationship nominally persists. TR and RELX are not simply losing seats as headcount falls. The revenue density per matter is expected to come under significant pressure as AI handles volume that previously required billable human time. The subscription that once covered fifty lawyers doing fifty research tasks may in future cover five lawyers supervising fifty automated workflows - at a fraction of the per-unit revenue.
The historic model fails not as a result of competitive displacement but through economic compression at source.
The plain fact is that as law is commoditised many will decide that the commercial risk of not having the most up to date legal analysis outweighs the commercial cash and delay costs of instructing lawyers. I call this the Good Enough thesis. In turn that leads to the Consumption Paradox - when the consumption of legal advice sky-rockets but the demand for lawyers plummets. We will look back and see that AI has made abundant that which was scarce, and that abundance results in value erosion for those who traded off scarcity.
A shrinking lawyer population is not a problem TR and RELX can solve by building a better product. It is a structural threat to the customer channel itself. And it demands a response that goes beyond product improvement.
The Trojan Horse - and who opened the gates
The common framing is that Anthropic is the threat - a technology giant moving directly into legal, building capability that competes with established legal research platforms. It may be Microsoft which owns lawyers in their Office suite, OpenAI which is investing billions in securing new markets, xAI which has quietly been recruiting more lawyers than any business could need, or it could be one of several dozen other models or suppliers, but today Anthropic is flavour of the month.
Part of today’s framing is true, but in reality it is mostly misguided.
Anthropic’s road map is plain to read:
Today: a Word plug-in targeted at legal workflows, enterprise positioning, direct marketing to law firms and in-house teams.
Tomorrow: a utility type service that embeds legal advice into the single do (nearly) everything subscription.
The mobile network EE (Everything Everywhere) was so ahead of its time when it adopted its name. Unfortunately for it, that accolade really goes to the big AI models. Perhaps the network’s residual value is now in that name?
The lawyers themselves opened the gates for the challenges that will “slim them down” and - perhaps - ultimately eviscerate many of them. It is that reduction that results in the legal publishers’ route to market contracting, and perhaps being lost. An irony, of course, is that the legal publishers themselves were in part instrumental to the process by inviting lawyers to write for them, normalising the process of lawyers giving their intellectual property rights away - sometimes to promote themselves, and, dare I say it, succumbing to the flattery of self-promotion. The process was accelerated, very dramatically, by the AI Legal Tech industry.
Law firms and in-house teams have enthusiastically deployed CoCounsel, Harvey, Legora and a growing list of legal AI tools - built on Anthropic’s Claude, OpenAI’s ChatGPT or comparable foundational models. In doing so, they have fed decades of accumulated legal knowledge directly into the foundational model ecosystems. But the more consequential dynamic is not what has been fed into the training corpus. It is what is being codified in real time. Lawyers are not just using these systems. They are encoding workflows - the sequences of judgement, retrieval, verification and drafting that constitute legal practice - in ways that can be abstracted, learned and scaled. That is process capture. And it is the Trojan Horse argument in its strongest form.
Anthropic’s partnership with Freshfields - deploying Claude across more than 5,500 staff in 33 offices and co-building commercial legal AI tools - is the thesis made visible. This is no longer a prediction. It is a live deployment. The tools lawyers are deploying have moved from reactive assistants to autonomous agentic systems - capable of initiating research, drafting and verification workflows without step-by-step human instruction. The process capture is accelerating accordingly.
The foundational models learn. Their legal capability grows. And as it grows, Anthropic’s ability to serve clients directly - bypassing the law firms and the research platforms - strengthens with every interaction.
Thomson Reuters has followed an equivalent path through acquisition. Its $650m purchase of Casetext - the company behind CoCounsel - gave it an AI-native application layer to fold into its Westlaw content position. Its partnership with Microsoft, embedding Westlaw and Practical Law into Microsoft 365 Copilot, goes further still: TR content reaching clients inside the workflow platform they already use, without a lawyer or a dedicated legal research session in the loop. That is the infrastructure pivot made visible for TR - and it mirrors, in its own way, the dynamic the Freshfields/Anthropic deal represents for the general model providers.
This is the Trojan Horse. Not Anthropic forcing entry but lawyers and legal tech providers collectively inviting it inside the legal citadel, interaction by interaction, subscription by subscription. TR and RELX have unavoidably but unwittingly contributed to this dynamic by supplying the knowledge infrastructure that powers the law firms. In doing so, they have helped build the capability of their most significant long-term challenger.
The good enough threshold does the rest. The moment Anthropic’s legal capability is sufficient for the client’s purpose - not perfect, not partner-grade, but good enough - the instruction is never made, the lawyer is not instructed and the subscription loses another justification. Good enough, embedded in the client’s own workflow is the combination that converts hesitation into action.
It does not need to be better than Westlaw or LexisNexis. It needs to be sufficiently commercially compelling - good enough - not to need them. Yes there is risk - but in many commercial matters, clients will accept imperfect legal completeness where the cost, speed and convenience trade-off is sufficiently compelling.
What the moat is actually made of
Before examining the pressures on the moat, it is worth thinking about what it actually comprises. The analysis that stops at curated data misses the more important half of the argument.
The data is the foundation. But the structure built on top of it enhances the moat’s defensibility - at least for now.
KeyCite and Shepard’s, the citator systems operated by TR and RELX respectively, are not simple research tools. They are not content. They are trust primitives - real-time truth infrastructure on which professional liability depends. A lawyer who relies on a case that has been overturned, and who failed to verify its citator status, faces a potentially serious professional conduct question. Sullivan & Cromwell knows the damage of relying on unverified (hallucinated) data points. The regulatory and negligence exposure is real. That is not a convenience problem. It is a professional obligation that carries personal liability consequences.
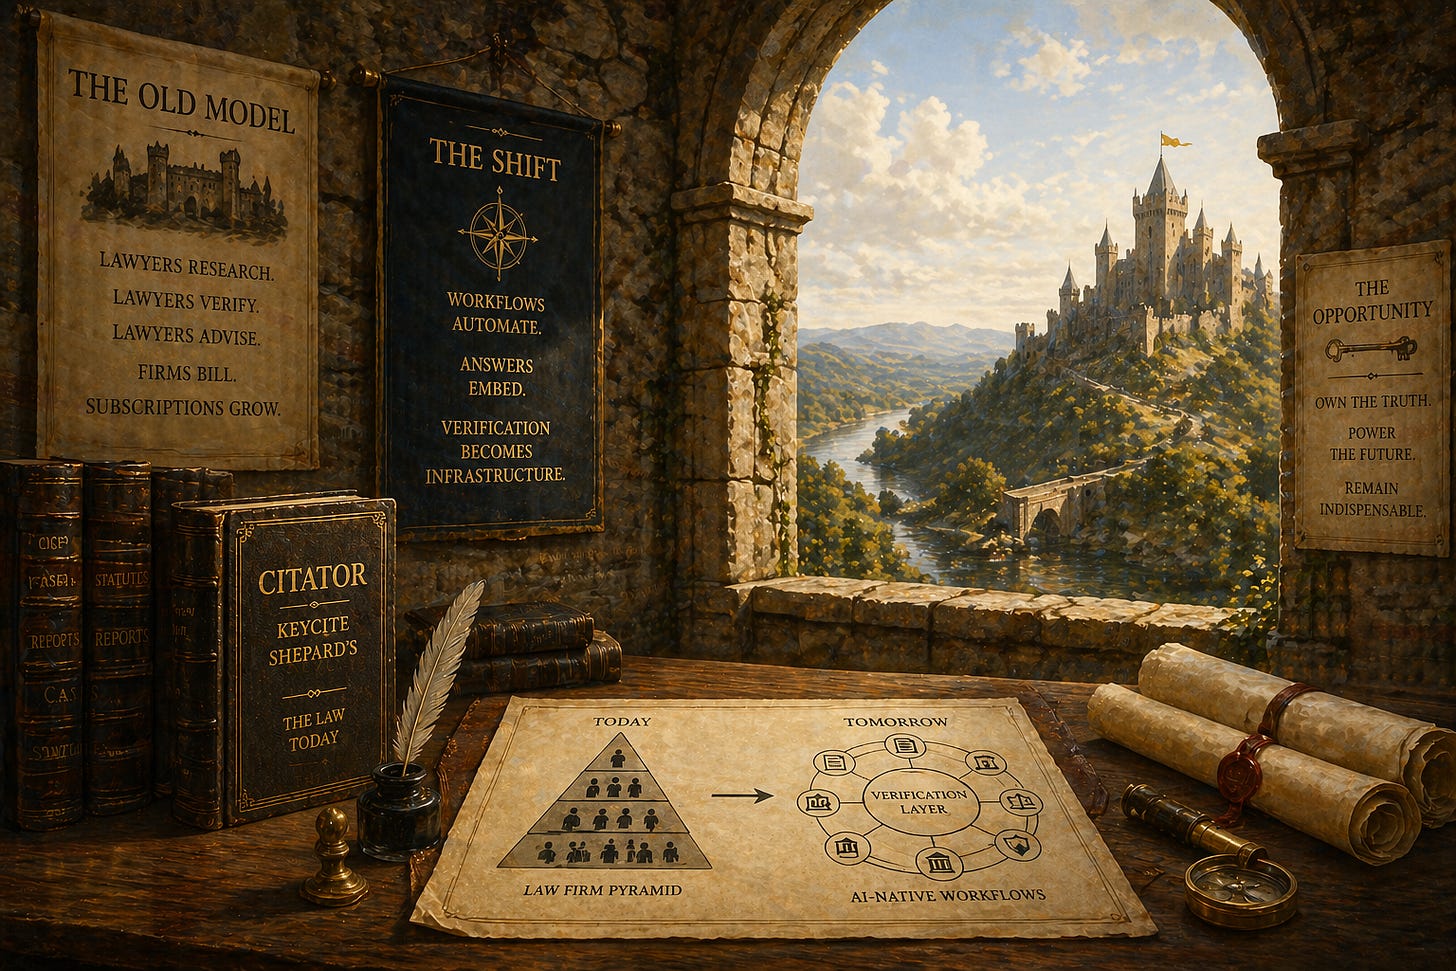
Critically, a standalone AI model only knows what it has been trained on. Legal AI systems connected to live authoritative sources can reach further - but the strategic question is who controls that connection, and on what terms. A standalone AI model does not know what a judge decided this morning; the citator is not simply a database of past decisions. The value-add is a live feed of legal reality, updated continuously, giving lawyers the assurance that the authority they are relying on has not been undermined since they last checked. That is a fundamentally different value proposition from static data retrieval and linguistic analysis. It is the difference between a library and a news wire. The strategic question is who owns that live connection.
There is a further dimension to the moat that the disruption narrative consistently underplays. TR and RELX's balance sheet credibility and data pedigree function as a professional liability backstop in a way that no start-up can replicate. As AI-generated legal outputs have led to documented court sanctions in cases where hallucinated citations reached judges, the value of a professionally defensible, verified source has increased rather than diminished. A law firm using Westlaw or LexisNexis is not merely buying data. It is buying the institutional credibility that the data has been curated, verified and is professionally defensible. No venture-backed legal AI start-up can offer that assurance with equivalent conviction. That asymmetry is real and should not be conceded lightly.
This distinction matters because the value in legal AI is shifting from producing answers to proving they are correct. Generation - drafting, summarising, researching - is commoditising rapidly. Verification - is this right, current, binding, applicable - remains scarce.
In a world of probabilistic AI outputs, the ability to determine what is still good law becomes more, not less, valuable. Leading firms already report efficiency gains of 30 to 60 percent in research and document review tasks. As those gains compound, the premium on verified, authoritative output rises.
Nonetheless there is vulnerability in this position. Citator functionality - checking whether a case remains good law, tracing its subsequent treatment, identifying whether it has been distinguished or overruled - is precisely the kind of verifiable, systematic task at which AI excels. It is exhaustive cross-referencing at scale. That is a description of what Anthropic and its peers are building towards with every iteration.
The professional anxiety that drives lawyers to citators will not save the citator business. It will drive lawyers to whatever tool most reliably satisfies the compliance obligation - regardless of who provides it. The moat, at that point, is not the citator functionality. It is the depth, authority and real-time currency of the underlying dataset on which any verification depends. That distinction is critical and the window in which it remains decisive is narrowing.
Two separate arguments: lawyers and data providers
This is the point at which analysis most frequently loses its clarity.
The challenge for lawyers and the challenge for TR and RELX run in parallel but they are not the same argument. Conflating them produces conclusions that are true in general and precise about nothing.
For lawyers, the disruption is to their role as the indispensable intermediary between the client and the legal answer.
As the lawyers’ role reduces the research function also diminishes. The citator-checking function is replicated by AI. The information filter role - the lawyer as the person who decides what is relevant and what to present - is undercut by AI that has access to everything the client knows, without the curation bias that every human instruction inevitably carries. The embedded judgement that lawyers developed through transactional immersion - knowing the players, the history, the arguments - erodes when AI handles the mechanics and the lawyer arrives late to the matter. The conditions that made judgement valuable are dismantled alongside the tasks that built it.
The first casualties are the legal tasks that made large numbers of lawyers economically necessary. The lawyers follow.
For TR and RELX, the disruption mechanism is different but consequentially linked.
Lawyers are the transmission channel through which the disruption reaches the data providers. As lawyers lose their research role, demand for research platforms contracts. As AI replicates citator functionality within integrated workflows, the standalone citator subscription loses its justification. As clients begin to self-serve - using AI tools embedded in their own enterprise systems - the instruction to the lawyer that previously generated the Westlaw search is never made.
The data providers do not lose because AI beats their product on its own terms. They lose because the human intermediary who needed their product is progressively removed from the loop, and because the clients who generated that demand find the instruction unnecessary.
Research becoming invisible
There is a further dimension that sits beneath the demand erosion argument.
Research is not just becoming cheaper. It is becoming invisible.
Legal answers increasingly appear inside workflows - within the document being drafted, within the email being composed, within the enterprise management system tracking contractual performance in real time. Citations become backend artefacts, generated automatically and verified in the background, rather than the product of a deliberate user journey through a research platform.
In that world, the question is not which research platform the lawyer prefers. It is whether the lawyer opens a research platform at all. The session that sustained the subscription model does not become a shorter session. It ceases to be a session.
That is where Westlaw and LexisNexis are most profoundly exposed. Not to a better research tool, but to a world in which lawyers stop needing to research at all - at least in the way that currently generates subscription revenue.
The answer is becoming certified, not searched
The next legal research product may not look like research at all. It may look like a verified answer - generated inside Word, Harvey, Luminance or an in-house contract system, with a citation trail behind it and a liability-grade certificate attached to it.
That distinction matters. Lawyers paid for research platforms because they needed to find and verify the answer. AI-native users will pay for proof that the answer can be relied on.
The most valuable product may not be the answer. It may be the certificate attached to the answer.
TR and RELX are the only entities with the balance sheet credibility, data pedigree and citator infrastructure to issue that certificate with professional conviction. No venture-backed legal AI startup can replicate that assurance. The commercial prize moves from search to certification - and the incumbents are better placed than anyone to own it.
Two directions of drainage
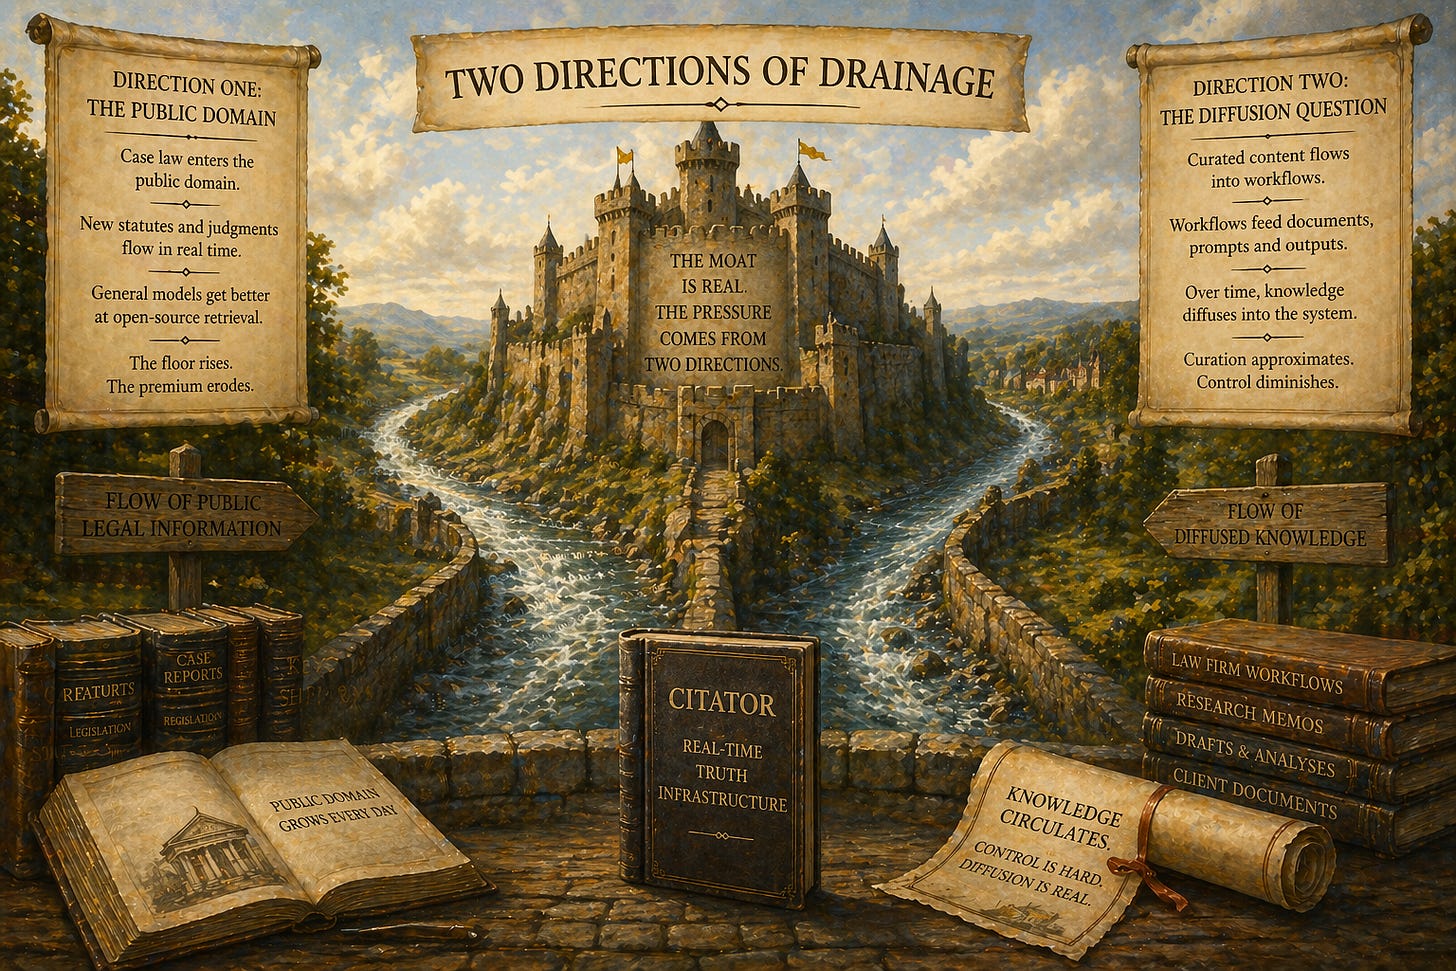
Direction one: the public domain
Legal information does not stand still. Case law, legislation and regulatory guidance enter the public domain constantly. New statutes and new judgments are already being fed to the foundational models in near real time. The proportion of genuinely proprietary legal content shrinks with every passing year. As retrieval accuracy across open-source material improves, the marginal value of a curated database diminishes at the lower and mid tiers of legal research, even if it remains significant at the complex, high-stakes end.
The floor of what a general model can do rises. As it rises, the ceiling that justifies premium subscription costs comes under pressure from below. The real-time truth advantage - currently one of the most defensible elements of the citator model - is itself time-limited as foundational models develop faster and more reliable connections to live legal sources. And, of course, the Government controlled sources of that information will want to publish that content. So the perfect Push-Pull environment is already being established.
Government-led Open Justice initiatives in both the UK and the US have been progressively making primary law available in machine-readable, structured form - a process that is accelerating and that converts what was once a proprietary data capture challenge into a public utility. The UK's Find Case Law service and the US federal court data infrastructure have both expanded significantly in recent years. The drainage toward the public domain is no longer a slow leak. It is a structural shift sanctioned and accelerated by the state.
Direction two: the diffusion question
There is no reliable public evidence that TR or RELX have directly licensed their core databases to foundational model providers. The indirect risk is more nuanced.
Law firms have subscribed to Westlaw and LexisNexis for decades. That content has been absorbed into their workflows, their research processes and their document production. Foundational models have been trained on vast quantities of legal material. How much of that material originated from curated legal databases, mediated through professional use rather than direct licensing, is genuinely unknown.
Enterprise safeguards are improving and modern frontier models are not typically trained directly on proprietary databases post-deployment. But the question of gradual diffusion - of curated content approximating into the general training corpus through years of professional use - is not naive. It would, however, be naive not to ask it.
Compare this with the major management consultancies. McKinsey, BCG and Bain kept their proprietary methodologies internal in a way the data giants structurally could not. Their core frameworks were never systematically commercialised through subscription access in the same way. The legal data giants face a structural exposure the consultancies do not - their content circulates widely, by design, and the downstream consequences of that circulation are difficult to monitor and impossible to fully control.
The remaining moat - and its limitations
Harvey, Legora and Clio have every commercial incentive to identify and capture legal content that falls outside client-specific protection. They are doing so. But there is an important constraint that the disruption narrative tends to underplay.
Until those challengers build their own authoritative legal databases - which is expensive, slow and legally complex - they remain dependent, directly or indirectly, on the content that TR and RELX have spent decades assembling. The depth, the verification, the editorial layer, the real-time citator infrastructure - none of that is replicable quickly. That dependency is the genuine remaining moat.
That dependency is narrowing. Legora's acquisition of Qura - explicitly positioned as a move to build the world's leading AI-native legal research platform - signals that the application layer is now actively constructing its own research capability rather than waiting for the data giants to license theirs.
Harvey has confirmed this empirically: it has scrapped its proprietary legal AI model after frontier models from Anthropic, Google and OpenAI outperformed it on Harvey's own internal benchmarks. Harvey has concluded empirically what this essay argues analytically: the model layer commoditises. The data layer does not. Harvey now aggregates data from LexisNexis, Wolters Kluwer and a custom OpenAI case law model rather than building its own. The challengers are not replacing the data moat. They are proving it is indispensable.
There is a further complexity worth noting. The Lexis venture arm has invested in both Harvey and EvenUp. More significantly, LexisNexis has integrated its primary law and Shepard's Citations directly into Harvey's platform through a strategic partnership described by one leading industry analyst as “possibly the most important legal tech move in a decade”. That is not incoherence. It is a hedge. But it raises a precise strategic question: is RELX positioning itself as the infrastructure layer beneath the application layer it is simultaneously funding and partnering - or is it licensing its most valuable asset into a platform that may ultimately commoditise it? The answer to that question matters enormously for what comes next.
LexisNexis has also announced a strategic alliance with Luminance, extending its authoritative legal content into enterprise contract workflows. That move is significant because it identifies the immediate battleground precisely. The in-house contract workflow - not the law firm library - is where the old instruction to the external lawyer is most likely to disappear first. The customer is not simply compressing. In some segments it is reappearing somewhere else entirely: inside the enterprise, without a law firm in the loop. As one senior Legal Ops professional with twelve years across Cisco, Spotify and Netflix has observed, most of the institutional risk and value sits not before the signature page but after it - in the obligations, renewals and indemnities buried in agreements that nobody is tracking. That is precisely the layer the LexisNexis/Luminance alliance is designed to own.
Harvey has moved in the same direction through its partnership with Ironclad, the contract lifecycle management platform. The integration allows Harvey to surface regulatory and legal changes affecting existing agreements, with Ironclad then operationalising those findings - amending templates, routing approvals and tracking new obligations. That is not pre-signature legal work. It is the post-signature data layer: obligations nobody tracks, renewals nobody monitors, indemnities buried in agreements from three years ago that nobody remembers. The application layer is moving downstream to where the institutional risk actually lives.
The pattern is not unique to RELX. Wolters Kluwer, the third major legal data incumbent, has executed an almost identical strategy - acquiring Libra Technology, a Berlin-based legal AI platform, in November 2025 for up to €90m, while simultaneously licensing its US and German primary law content to Harvey.
Major legal data incumbents are now licensing authoritative content into the same dominant emerging application-layer platform. The strategic coherence of each individual move is defensible. The collective effect - multiple incumbents licensing into a single aggregator now valued at $11bn - raises a precise and uncomfortable question: are the data giants licensing their way to relevance, or licensing their way to irrelevance?
The challengers have recognised this themselves. Legora's acquisition of Graceview - a regulatory horizon scanning platform monitoring tens of thousands of official sources across more than 100 jurisdictions in real time - is evidence that the application layer knows where the strategic prize actually sits. The race to own the data layer has begun from both ends of the market simultaneously.
RELX’s recent proposed acquisition of Doctrine (announced in late April 2026) - a French legal AI platform serving 27,000 legal professionals across civil law jurisdictions in France, Italy, Germany and Spain - suggests the latter may be closer to the truth: Doctrine combines a comprehensive corpus of civil law case law and legislation with AI-powered research, drafting and analytics tools. LexisNexis has historically been thinner in civil law jurisdictions than in common law markets. This is therefore not defensive consolidation of overlapping content. It is territorial expansion into jurisdictions where the data moat needed strengthening, executed at precisely the moment the application layer is most vulnerable to consolidation. That is strategically coherent.
The strategic question is not whether the moat exists. It does. But the more urgent question - given that all three major legal data incumbents are now licensing their core content into the same application-layer aggregator - is whether that moat remains individually owned, or has been collectively diluted by the very partnerships designed to defend it. The window to resolve that question is open. It is not open indefinitely.
There is, however, one element of the moat that the “drainage” analysis underplays. While public law is progressively commoditising, TR and RELX still own something that cannot be reconstructed from public sources: the accumulated private market intelligence embedded in products such as Practical Law for Companies (PLC). This is not case law. It is distilled transactional know-how - market-standard positions, precedent language, risk tolerances, drafting conventions - built from decades of practitioner input and editorial curation. In a world where every AI model knows the law, the premium value shifts to knowing the market. That distinction may not yet be widely understood, and it represents the most durable and least replicable element of what TR and RELX actually own. The law tells you what is permitted. Market intelligence tells you what will clear. The strategic question is whether they recognise it as such - and gate it accordingly rather than allowing it to diffuse into the same licensing arrangements that are commoditising their primary law content.
The overlap question
Whether TR and RELX can both prevail through this period depends in part on a question that has not been answered publicly: how much do their core datasets actually overlap?
In primary law - cases, legislation, regulatory material - the overlap is substantial. Both platforms cover the same jurisdictions, the same courts, the same statutory frameworks. At that level, competitive differentiation is thin.
The meaningful divergence lies in the editorial layer. The citators operate differently. The analytical and commentary content differs. The proprietary databases - practice guides, specialist journals, transaction intelligence - are not identical. There is genuine differentiation in the structure built on top of the primary law, even where the primary law itself is shared.
The proposed Doctrine acquisition adds a further dimension to this analysis. TR's Westlaw has historically had stronger common law coverage; RELX through Doctrine would strengthen its civil law coverage across continental Europe. If that jurisdictional divergence holds and deepens, it provides a basis for a defensible two-incumbent market - each dominant in different legal traditions, with genuine differentiation at the primary law layer rather than only at the editorial layer above it. Whether that divergence is intentional strategy or convenient rationalisation of an opportunistic deal remains to be seen.
If competitive pressure concentrates on the primary law layer - where general model improvement is fastest - both platforms are exposed in the same direction simultaneously. If either accelerates differentiation at the editorial and analytical layer, the defence becomes more credible. Whether the market sustains two premium incumbents under equivalent pressure from the same direction is a question both boards should be modelling now.
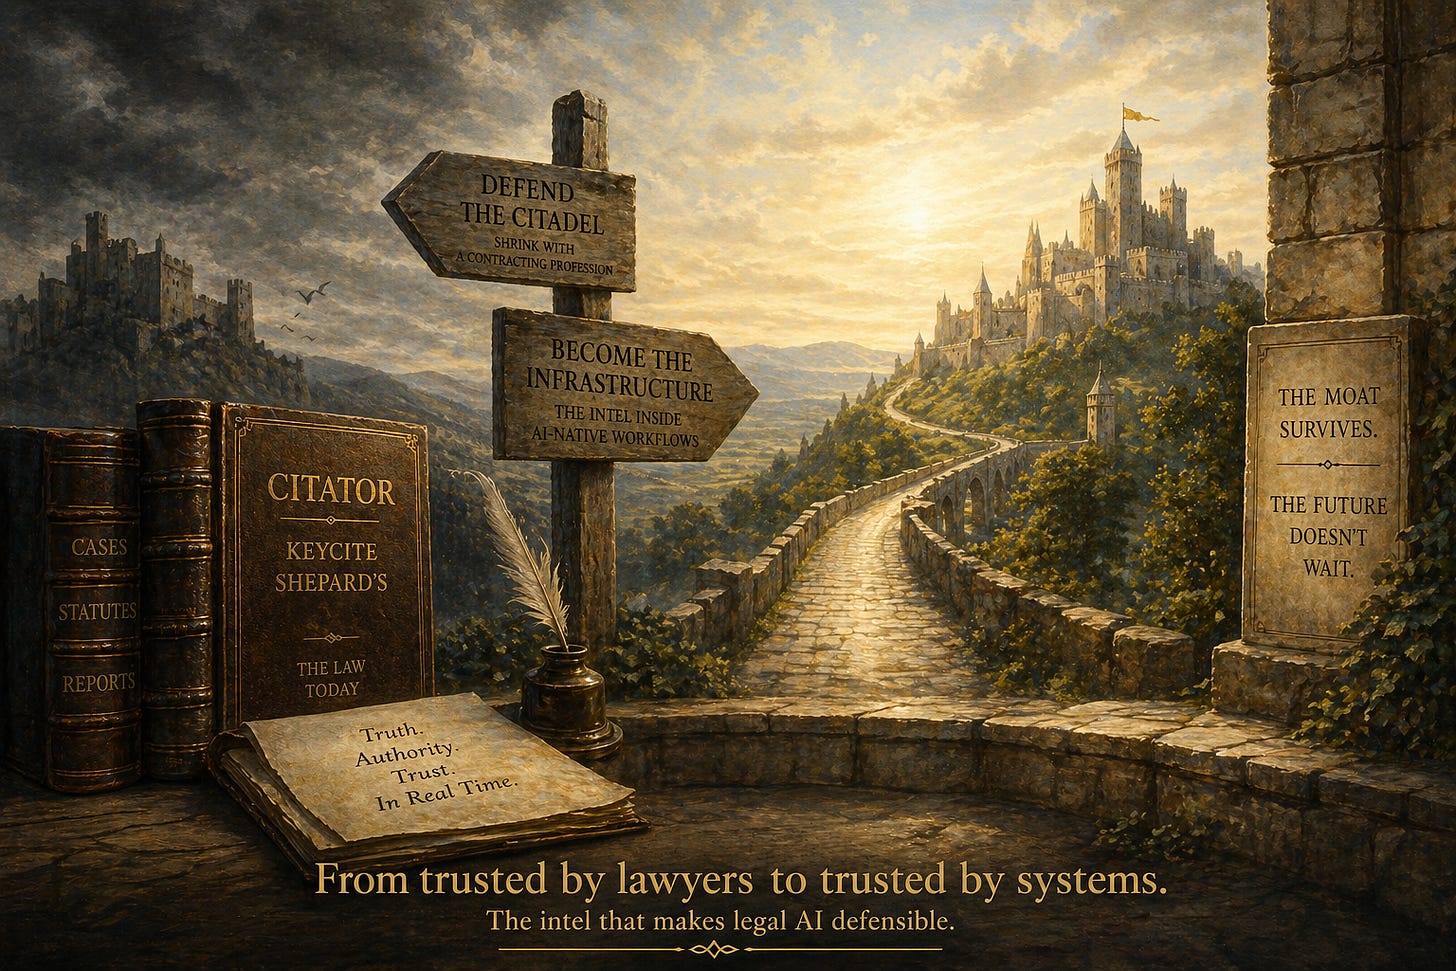
The strategic choice: defend the citadel or become the infrastructure
For TR and RELX, the strategic options are harsh. At their simplest they reduce to two orientations - but the infrastructure path has more than one form, and the most aggressive of them has not yet been widely discussed.
Defend the citadel means remaining loyal to the law firm as the primary customer - investing in product improvement, deepening workflow integration, extending the citator and editorial layer and competing for the legal tech budget of a profession that is itself under structural pressure. This is the path of least strategic disruption. It is also, in the long run, the path of managed decline. A compressing lawyer population is not a problem a better product solves.
Become the infrastructure means following the client to where they are going - inside AI platforms, inside enterprise management systems, inside the workflows where legal answers are increasingly generated without a lawyer in the room. In this model, TR and RELX do not compete with Anthropic, Microsoft or Google. They become the authoritative data and verification layer - the intel inside - that makes AI-generated legal output professionally defensible.
The mechanism for this pivot is already visible. The foundational models need verified, real-time legal data to be trusted in professional contexts. Every AI-generated legal output that reaches a court or a boardroom without verified citation carries liability risk for someone. TR and RELX are better placed than anyone to provide the grounding layer that mitigates that risk - not by selling subscriptions to lawyers but by licensing real-time truth infrastructure to the platforms that are replacing the lawyers’ research function.
Both TR and RELX have begun executing versions of this pivot. TR's integration of Westlaw and Practical Law into Microsoft 365 Copilot embeds its authoritative content into the workflow platform used by millions of professionals, with or without a lawyer in the loop. RELX's integration of Shepard's Citations into Harvey's platform deploys its citator infrastructure inside the dominant emerging legal AI application. RELX's proposed acquisition of Doctrine and TR's acquisition of Casetext both represent the folding of AI-native workflow capability into an authoritative content position. The strategic direction, for both companies, is right. The execution risk - whether the integration preserves the AI-native agility of what has been acquired or absorbs it into the slower cadence of a large incumbent - is the question their boards should be asking now.
The most important evidence for the thesis is not what the challengers are saying. It is what the incumbents are doing. TR is pushing Westlaw and Practical Law into Microsoft 365 - into Word, Teams, Outlook and SharePoint. LexisNexis is pushing Shepard's and its legal content into Harvey and Luminance. Both are moving from legal research as a destination to legal verification as embedded infrastructure. The direction is right. The urgency is the question.
Harvey is launching its own Microsoft 365 Copilot integration in Q2 2026. TR and Harvey will be embedded in the same workflow platform simultaneously - competing for the same embedded position inside the same lawyer's working environment. That collision will be instructive.
There is a further dimension to the infrastructure pivot that has not yet been widely discussed. In May 2026 Will Chen, an erstwhile major firm lawyer and “hobbyist” developer built Mike OSS - a self-hostable open-source legal AI platform claiming feature parity with Harvey and Legora - in two weeks using Claude. Half the legal tech industry immediately began questioning whether billion-dollar valuations built on the application layer were wrappers waiting to be commoditised. They were asking the right question - but about the wrong layer. Open-source legal AI platforms are beginning to emerge - self-hostable, zero licensing cost, built on the same foundational models as Harvey and Legora, and designed for law firms that want control over their own data and infrastructure. Their critical weakness is precisely what TR and RELX have in abundance: verified, curated, real-time legal data.
The logic is straightforward. An open-source platform distributed freely, with TR or RELX data embedded as the verification layer, converts the data giant from a subscription business into infrastructure. The application is free. The data is the product. The firm that cannot afford Westlaw at enterprise pricing may very well adopt a self-hosted tool backed by Westlaw data at consumption pricing. The business with an in-house function that cannot justify LexisNexis may pay for metered access as and when it needs it.
The new distribution channel widens precisely as the traditional one narrows.
The remaining questions are whether they buy an existing open-source legal solution or develop their own, and whether they market to law firms, go direct-to-consumer or adopt a dual approach. These are execution questions, not strategic ones. The strategic direction is already answered by the logic of the pivot itself.
This is not a defensive move. It is the infrastructure pivot in its most aggressive form.
The two paths are not mutually exclusive in the near term. It would be commercially rational for TR and RELX to continue collecting subscriptions from the law firms that remain active customers while simultaneously developing licensing relationships with the foundational model providers who are building the platforms that will ultimately replace those customers. That is not contradiction. It is a hedge - and a strategically intelligent one, provided it is executed with sufficient urgency and on terms that preserve the editorial and verification layer as a distinct and defensible asset rather than commoditising it into a passive data feed.
The risk in the licensing path is real. Becoming a data supplier to the companies that are disintermediating the legal profession is not a strategy if it means surrendering the editorial and verification layer in the process. The sustainable position is one in which TR and RELX own the real-time truth infrastructure that makes AI-generated legal outputs professionally defensible - and licence access to that infrastructure on terms that preserve its value rather than erode it.
The speed imperative
Whatever strategic path is chosen, the speed at which it is pursued is not a secondary consideration. It is the primary one.
The citator advantage is itself time-limited. New case law and new statutes are already being fed to the foundational models in near real time. The proprietary advantage in primary law is eroding faster than either company may be modelling. The window to establish the verification layer as indispensable infrastructure - before the general models develop sufficient reliability to satisfy the professional compliance obligation on their own - is the strategic race that cannot be run slowly.
CoCounsel’s citation ledger architecture is the right instinct. A session-verifiable evidence trail, ensuring the agent cites only what it actually retrieved, addresses the hallucination problem at the architecture level. That is sophisticated and it matters. But it is a product response to a challenge that also requires a market positioning response.
One further point on timing. Multi-year enterprise contracts - typically running between one and five years across law firm purchasing - create a lag between the structural shift and the revenue impact. That lag may create a false sense of security. Renewal conversations that feel distant today will arrive quickly, and the firms having those conversations in two or three years will be doing so in a materially different market. Contractual lock-in buys time. It does not change the destination.
The question is not whether TR and RELX are capable of making the pivot. They are. The question is whether they are moving with sufficient urgency to make it before the window closes.
The conclusion
Thomson Reuters and RELX built the infrastructure of modern legal practice. That is not a small thing. The depth of their data, the authority of their citator systems, the editorial judgement embedded in their platforms and the trust attached to their brands remain genuine competitive advantages that no general model can replicate overnight.
But the moat was built for a world in which legal research was a conscious, deliberate professional activity conducted by lawyers whose firms paid for the tools to do it. That world is changing. The law firm is no longer the dominant distribution channel it once was. Research is becoming invisible. The user journey that sustained the subscription model is shortening - and in some cases disappearing entirely.
The moat survives. But only if it is redefined.
The citator systems, the editorial layer, the real-time truth infrastructure - these are not legacy assets to be defended. They are the foundation of AI-native legal workflows that do not yet exist at scale but will. The data giants are better placed than anyone to become the intel inside those workflows - the authoritative grounding layer without which AI-generated legal output cannot be trusted in a professional context.
RELX's proposed acquisition of Doctrine, its integration of Shepard's Citations into Harvey's platform, and TR's embedding of Westlaw into Microsoft 365 Copilot all suggest that at least some of the right moves are already being made. The question is whether they are being made with sufficient coherence and urgency - and whether the licensing strategy that embeds their content into emerging platforms preserves their value or gradually surrenders it.
There is a larger argument in the background to this which demands consideration: if AI compresses the volume of junior legal work, fewer people enter the profession at the base, and the pyramid hollows from the bottom upward. Few doubt that there will be fewer lawyers, the “better question” is whether the lawyers who remain will be able to provide what they currently claim as their irreplaceable value layer - that is what they usually describe as “judgement” - the capacity to understand the characters, the deal drivers, the history and the dynamics of a transaction. Lawyers claim it as uniquely theirs. But it is not innate. It is acquired through immersion - through being at the table from the very beginning, absorbing context that is never written down. If AI handles the mechanics sufficiently well that lawyers are only invited in when judgement is required, they will arrive without the embedded context that made their judgement valuable in the first place. They will need to be briefed. And others can be briefed equally well. Indeed others may be better trained for that role: nothing in law school prepares a lawyer to provide that service without the transactional immersion that AI is now beginning to displace (and little at the law school I attended trained us for that role in any event). That is the profession’s deeper dilemma - but this essay focusses on the data giants, not the owners of the fortresses.
In short, the risk is not that AI replaces Westlaw and LexisNexis. The risk is that lawyers stop needing to research at all - and that when the verification infrastructure for an AI-native legal world is built, someone else builds it.
Defend the citadel, and shrink alongside the profession it serves. Become the infrastructure, and the profession’s disruption becomes your opportunity.
That is the data giants’ dilemma. It demands a strategy, not a press release. And it demands one now.
Quentin Solt is a senior UK commercial solicitor with over four decades of experience in corporate finance, M&A and technology-led businesses. He publishes using the #FactsAreFriends on LinkedIn and Substack.
With thanks to colleagues whose insights and challenge improved this analysis.
Sources and further reading
Financial foundations
Thomson Reuters full year 2025 results - Legal Professionals segment: https://ir.thomsonreuters.com/news-releases/news-release-details/thomson-reuters-reports-fourth-quarter-and-full-year-2025
RELX 2025 market segments report - LexisNexis Legal and Professional division: https://www.relx.com/~/media/Files/R/RELX-Group/documents/reports/annual-reports/2025-ar-sections/relx-2025-market-segments.pdf
Market context
Investors fear AI will undercut LexisNexis - Business Insider, March 2026: https://www.businessinsider.com/lexisnexis-exec-says-investors-ai-fears-are-misguided-2026-3
Thomson Reuters - strategic moves
Thomson Reuters acquisition of Casetext, August 2023: https://www.prnewswire.com/news-releases/thomson-reuters-completes-acquisition-of-casetext-inc-301903701.html
Thomson Reuters and Microsoft partnership - Westlaw and Practical Law into Microsoft 365: https://www.thomsonreuters.com/en-us/posts/innovation/thomson-reuters-and-microsoft-revolutionizing-professional-workflow
RELX/LexisNexis - strategic moves
LexisNexis and Harvey strategic alliance, June 2025: https://www.lexisnexis.com/community/pressroom/b/news/posts/lexisnexis-and-harvey-announce-strategic-alliance
LexisNexis and Luminance strategic alliance - enterprise contract workflows: https://www.lexisnexis.com/community/pressroom/b/news/posts/lexisnexis-and-luminance-announce-strategic-alliance
RELX proposed acquisition of Doctrine, April 2026: https://www.lexisnexis.com/community/pressroom/b/news/posts/relx-group-enters-into-agreement-to-acquire-french-legaltech-company-doctrine
Harvey and Ironclad strategic partnership, August 2025: https://ironcladapp.com/resources/articles/ironclad-harvey-partnership
Anthropic - direct legal market entry
Anthropic and Freshfields partnership, April 2026: https://www.freshfields.com/en/our-thinking/news/news-search/2026/04/freshfields-and-anthropic-team-up-to-co-build-ai-legal-workflows-deploying-claude-across-the-firm-globally
Wolters Kluwer - strategic moves
Wolters Kluwer acquisition of Libra Technology, November 2025: https://www.wolterskluwer.com/en/news/wolters-kluwer-to-acquire-legal-ai-assistant-software-provider-libra-technology-gmbh
Wolters Kluwer content licensing agreement with Harvey, August 2025: https://www.wolterskluwer.com/en/news/primary-press-release (search in site for “collaboration with Harvey”, dated August 08, 2025)
Open Justice and public domain
UK Find Case Law service - National Archives: https://caselaw.nationalarchives.gov.uk
US federal court data - CourtListener: https://www.courtlistener.com
Open-source legal AI
Mike OSS - open-source legal AI platform built by Will Chen, former Latham and Watkins lawyer, May 2026: https://mikeoss.com
GitHub repository: https://github.com/willchen96/mike Artificial Lawyer interview with Will Chen: https://www.artificiallawyer.com/2026/05/04/mike-the-open-source-legal-ai-platform-will-chen-interview
Commentary and analysis
Sheikh Report - “Why Being First Has Never Meant Owning the Market”, April 2026 https://www.linkedin.com/newsletters/the-sheikh-report
Artificial Lawyer - Claude for Legal coverage, April 2026: https://www.artificiallawyer.com/2026/04/23/claude-can-absorb-up-to-40-of-inhouse-legal-tech-spend-claude