 Facts are friends
This is an unscheduled “PS” piece written in the light of what has happened in the month since I wrote the original essay. In this extension I look at the continued emergence and apparent domination of the legal market by Legora and Harvey and the recent announcement of mega-mergers between law firms.
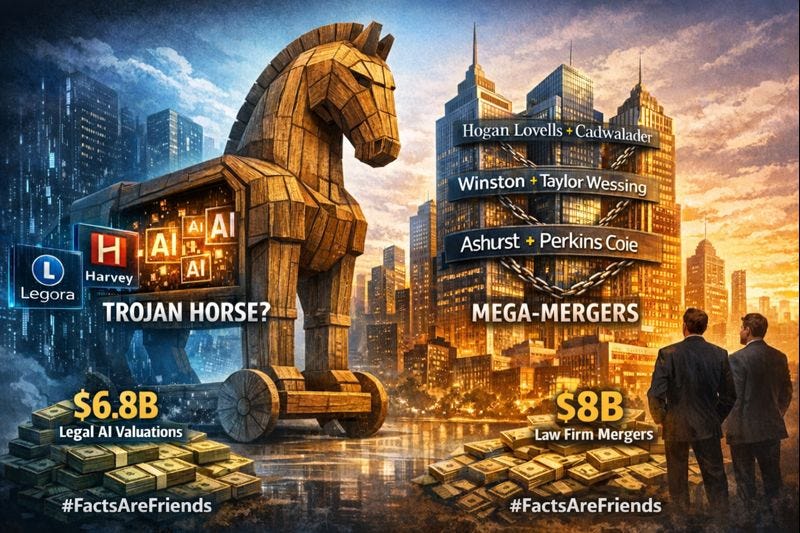
The thesis holds. A convergence of explosive legal AI revenue growth - Legora’s ARR leaping from $4 million to $40 million in under 18 months - alongside the largest law firm merger wave in history worth over $8 billion combined reveals a market where BigLaw is simultaneously purchasing the tools that commoditize legal work while scrambling for scale to survive the consequences.
Three mega-mergers announced within weeks of each other (Hogan Lovells-Cadwalader, Winston-Taylor Wessing, Ashurst-Perkins Coie) signal defensive consolidation, while Goldman Sachs’ widely-cited estimate that 44% of legal tasks are automatable explains why firms feel compelled to merge or be left behind.
Over the four previous essays, I argued that legal AI platforms command unprecedented 80x revenue multiples built on untested renewal cycles, that law firms are paying for Trojan Horses that commoditise their own expertise whilst consulting firms build protective moats, and that the real threat comes not from Harvey stealing drafting work but from Accenture stealing entire client relationships. The developments of late 2024 and 2025 provide a critical test of these arguments.
The Trojan Horse dynamic in legal AI valuations
The core contradiction at the heart of legal AI business models is stark: platforms must demonstrate efficiency to justify their valuations, but every efficiency gain proves legal work is more commoditized than premium billing rates suggest.
Industry analyst Shahrukh Khan captured this in a scathing June 2025 analysis:
“An AI product that promises the delivery of a quicker, and potentially better, work product flies in the face of financial logic. Billable hours for a certain gentry of clients will always be here to stay, including for even the work that is most automatable.”
Harvey, valued at $5 billion with approximately $100 million ARR, and Legora at $1.8 billion with an estimated $40 million ARR, trade at 45-50x revenue multiples - compared to 5-10x for typical SaaS companies.
These valuations require investors to believe legal AI will capture enormous value. That value must come from somewhere. As one Maginative analysis noted:
“It’s the classic innovator’s dilemma: the very firms paying for Harvey’s services might be funding their own disruption.”
The market has noticed the paradox. A PwC survey of Top-100 UK law firms revealed a dramatic sentiment shift: in 2023, 69% expected AI to lift revenue and margins, but by 2025, only 31% held that view - with two-thirds now expecting negative impact as “clients increasingly expect efficiency gains to translate into reduced costs”.
Legora’s trajectory reveals acceleration of legal AI adoption
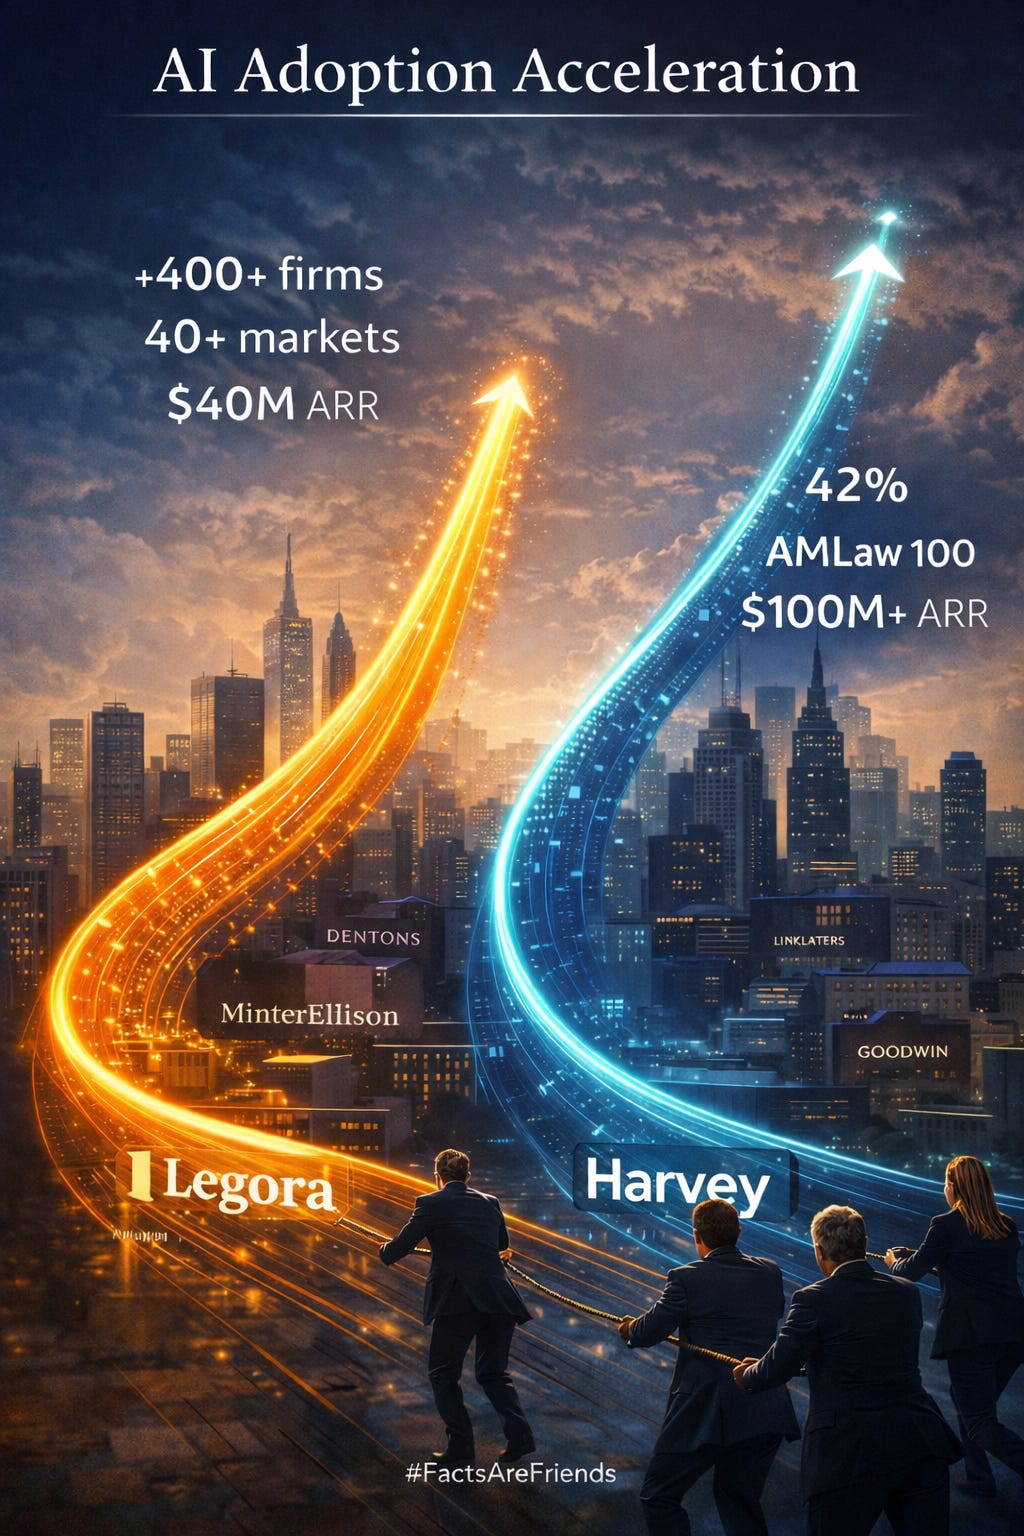
Legora’s growth provides concrete evidence of how quickly legal AI is penetrating BigLaw. The Swedish startup, formerly known as Leya, has experienced what CEO Max Junestrand calls “astronomical demand”:
Metric May 2025 October 2025 Change
Customer base 250 firms 400+ firms +60%
Markets served 20 40+ +100%
Estimated ARR $5-10M ~$40M 4-8x
Valuation $675M $1.8B 2.7x
The client list reads like a BigLaw directory: Linklaters, Cleary Gottlieb, Goodwin, MinterEllison, and Dentons (which deployed Legora Europe-wide in June 2025).
These are not experimental pilots at innovation-curious firms - they are firm-wide rollouts at elite institutions.
Competitor Harvey claims 42% penetration of the AmLaw 100, with average contracts around $223,000 per firm compared to Legora’s estimated $20-40K range, suggesting Legora may be capturing mid-market clients while Harvey dominates the largest firms.
In Part 1, I identified the core vulnerability: most of this explosive growth hasn’t survived a single renewal cycle. For companies doubling annually, renewals represent only 26% of revenue in Year 2, 37% in Year 3.
Legora’s 10x growth from $4M to $40M ARR means the vast majority of this revenue remains first-year subscriptions - the “AI tourist” phenomenon I warned about earlier. The growth, it seems, is real. The sustainability remains unproven.
The Sacra research report identified a critical dynamic:
“Early firm-wide rollouts demonstrate a proven playbook where small pilots expand into enterprise licenses that multiply seat counts by 10-20x”.
This land-and-expand model means current ARR figures likely understate future revenue, helping justify otherwise eye-watering valuations.
Three mega-mergers signal defensive consolidation seeking scale
The December 2025 announcement cascade:
Hogan Lovells- Cadwalader ($3.6B),
Winston-Taylor Wessing ($1.75B), and
Ashurst-Perkins Coie ($2.7B)
represents the most significant law firm consolidation in history. Combined, these deals will create firms with 7,500+ lawyers and $8+ billion in revenue.
Just what’s driving this urgency? I believe that scale economics now dominate strategic thinking.
David Morley, former Allen & Overy senior partner, articulated the new reality:
“It’s a scale game now - $1bn is quite small for a global firm, you need to be able to invest in top talent and AI to really differentiate yourself”.
This scramble for scale reflects the sentiment collapse I documented in Part 3: in 2023, 69% of Top-100 UK firms believed AI would increase revenue and margins. By November 2025, only 31% held that view - with two-thirds now expecting negative impact. The mega-mergers are not confidence. They are defensive consolidation by firms who recognise that AI efficiency gains will flow to clients, not to firms, unless they achieve economies of scale.
Kent Zimmermann of Zeughauser Group added:
“almost every firm outside the top 20 by PEP in the Am Law 100 is either pursuing a deal or talking about pursuing one”.
Technology investment pressures require spreading costs. The Ashurst-Perkins Coie announcement explicitly cited AI:
“Ashurst Perkins Coie, with the combined financial strength of both firms, will leverage the power of AI to transform the practice of law”.
Law.com analysis noted firms are “bringing in pricier business professionals” and that “it’s possible law firms will have to make much more substantial capital investments if this stuff really does take hold”.
The New York-London corridor is the strategic prize. Hogan Lovells CEO Miguel Zaldivar stated plainly:
“The most attractive legal market today, and the most lucrative market, is that New York-London corridor”.
Cadwalader’s position on Wall Street - despite losing 116 attorneys in 2025 - made it valuable enough to command participation in a $3.6B combination.
Evidence mounts for the commoditization thesis
Multiple data points suggest legal work is becoming commoditized despite the profession’s efforts to resist:
The ALSP market has exploded.
Alternative Legal Service Providers reached $28.5 billion with 18% compound annual growth, projected to hit $49.6 billion by 2033.
Some 57% of corporate law departments now use ALSPs, indicating clients have discovered they can unbundle legal work and pay less.
Clients are forcing the issue.
CLOC/Harbor 2025 survey found 26% of corporate legal departments expect to decrease law firm spending in 2026.
An innovation director at a Top 20 firm quoted in one analysis put it bluntly:
“We’ve had conversations with major clients that say, look, we expect AI to make things less expensive. You’re either gonna figure that out or we’re just gonna pay you 20% less next year”.
Leverage ratios are shifting.
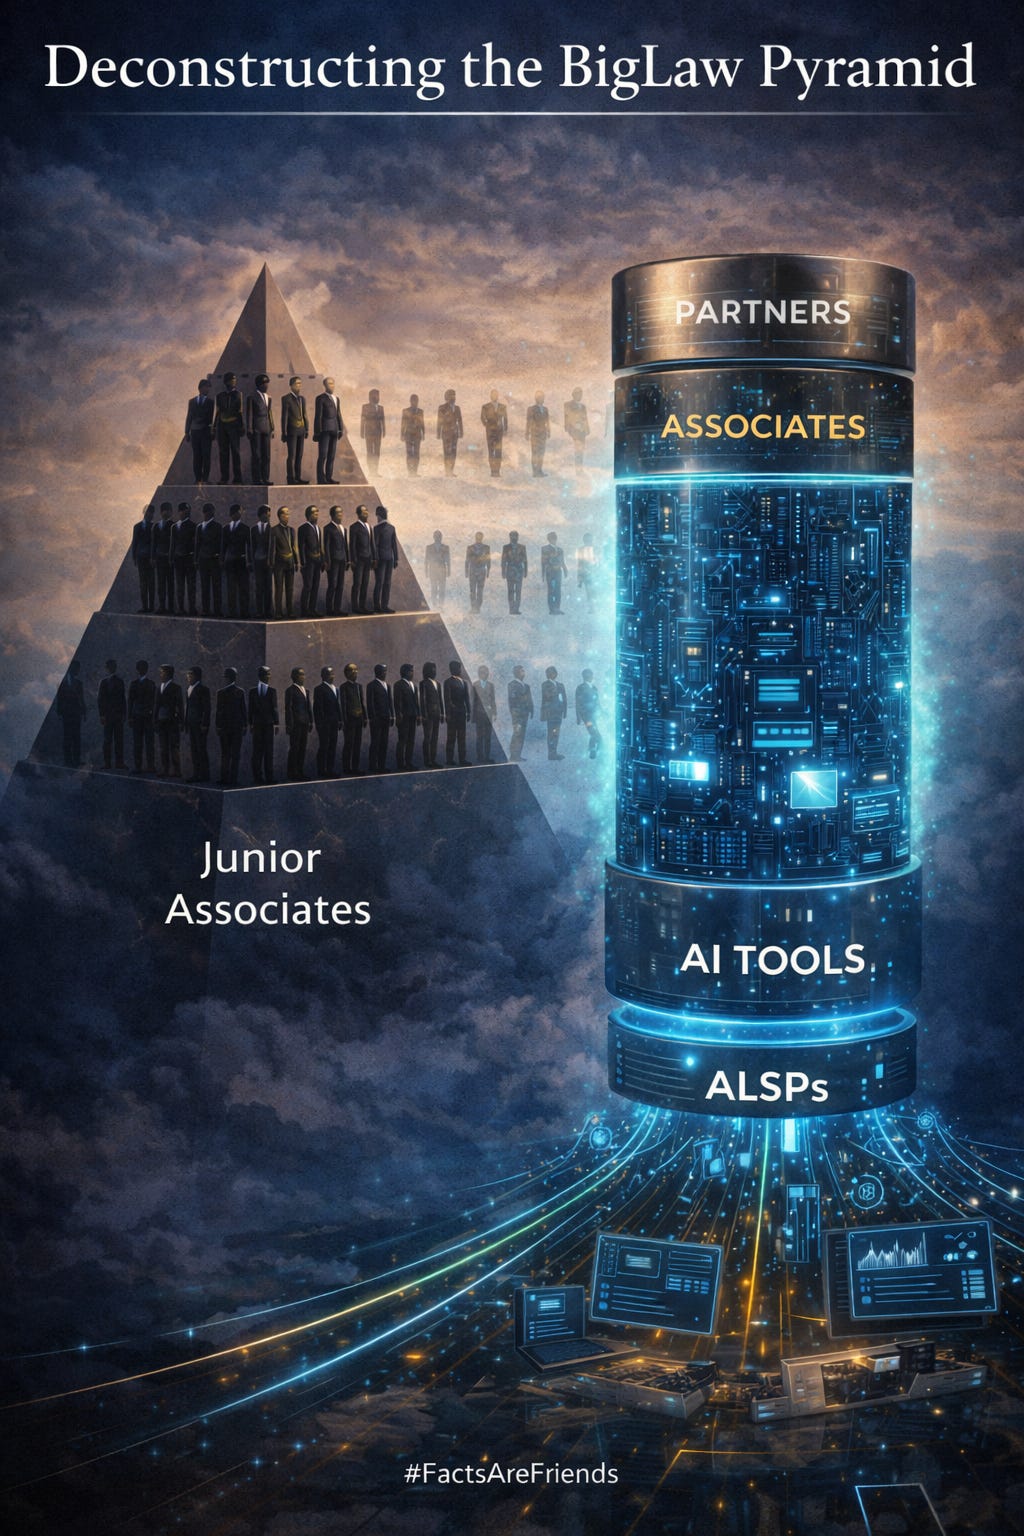
The Citigroup-Hildebrandt report found that while 86% of large firms plan to grow associates through 2027, only 35% intend to grow first-year classes - a “pyramid to cylinder” structural shift.
An unprecedented 63% of large firms expect AI to influence leverage ratios by 2035, suggesting the profession knows junior associate work is most exposed to automation.
Clifford Chance already made the first major AI-cited cuts.
In November 2025, the Magic Circle firm eliminated approximately 50 business services roles (~10% of London back-office staff), explicitly citing “increased use of AI” and “reduced demand for some business services”. This marks the first significant headcount reduction directly attributed to AI at a major global firm.
This is the Trojan Horse thesis from Part 2 made manifest.
I argued that when law firms deploy Harvey or Legora, they upload expertise, train their lawyers and - critically - train their clients to expect AI-assisted services.
The knowledge that was once rare becomes abundant. The mystique evaporates. Clifford Chance's November 2025 cuts - approximately 50 business services roles explicitly attributed to “increased use of AI” - represent the first major acknowledgment that the efficiency gains are real and that headcount implications follow.
The Harvard Law study reveals elite firms’ strategic confusion and cognitive dissonance
Harvard Law School’s Center on the Legal Profession conducted interviews with AmLaw 100 firm leaders that revealed both remarkable efficiency gains and strategic uncertainty:
On productivity: “Lawyers have seen productivity gains greater than 100 times” and “a complaint response system reduced associate time from 16 hours down to 3-4 minutes”.
On staffing: “None of the firms interviewed are anticipating any reduction in the need for the number of practicing attorneys” - despite those productivity gains.
On investment burden: “The magnitude of investment required will be difficult for many mid-sized firms, and it illuminates the competitive threat”.
On forced strategic thinking: “AI is a very wonderful gift in that it is a catalyst for the conversations about our business models and the scale of the firm that we would not have had without the AI opportunities”.
The contradiction is clear: firms acknowledge 100x productivity improvements while denying staffing implications.
This cognitive dissonance may reflect the reality that law firms remain highly profitable—revenue rose 11.3% in H1 2025, profits per equity partner grew 13.7%, and some partners now bill $3,000+ per hour.
This cognitive dissonance reflects the regulatory trap I identified in Part 2: firms face extraordinary pressure around data privacy and compliance. Harvey and Legora maintain strict “zero training on customer data” policies. The platforms cannot build moats from firm knowledge. Yet firms are achieving 100x productivity improvements. Where does this efficiency go? To clients demanding lower fees. To platforms capturing subscription revenue. To everyone - except the law firms themselves.
For now, firms are absorbing AI as additional cost rather than replacement cost.
That is unlikely to remain sustainable for long.
The innovation leader’s “secret hesitancy”
Spellbook CEO Scott Stevenson captured a crucial dynamic:
“We see almost no hesitation from the small and mid-sized law firms we serve. Larger law firms are secretly hesitant due to the billable hour”.
This stands in stark contrast to the consulting firms' approach detailed in Part 2. McKinsey built Lilli on proprietary knowledge. BCG transformed to 20% AI revenue - $2.7 billion. They control the AI that captures their expertise. Law firms are hesitant to disrupt the billable hour, so they licence AI they don't control whilst teaching clients that legal analysis can be automated. The consulting firms saw the threat and built moats. Law firms are funding their own disruption whilst secretly hoping nothing fundamental changes.
This secret hesitancy explains why Shahrukh Khan argues firms buy AI primarily as marketing:
“The main reason why the large law firms are buying expensive AI products is because their clients want them to. The partner rank... could largely care less about the technological potential of a technology meant to disrupt a century-long revenue model”.
This hesitancy creates opportunity for AI vendors.
As firms licence tools for marketing purposes without deeply integrating them, they’re simultaneously training their clients to expect AI capabilities and funding the development of increasingly powerful platforms. The “data trojan horse” dynamic - where AI tools collect proprietary information from every matter, improving their capabilities over time - compounds this effect.
Legal AI platforms are becoming more capable with every contract reviewed, every brief drafted, every research question answered.
Conclusion: The evidence strongly supports the thesis
Recent developments provide substantial support for the proposition that legal AI platforms are teaching clients to commoditize legal work while law firms fund their own disruption through defensive consolidation.
Legora’s ARR trajectory demonstrates that legal AI adoption has reached escape velocity, with elite firms now deploying these tools firm-wide.
The mega-merger wave reflects firms’ recognition that scale is now existential - needed to spread technology investment, compete for talent, and maintain market position against both larger competitors and potentially AI-native challengers.
The commoditization evidence - from ALSP growth to client demands for price reductions to the Clifford Chance layoffs - shows that efficiency gains cannot be indefinitely captured by law firms.
The most telling indicator may be the sentiment reversal in PwC’s survey: from 69% expecting AI to boost revenue and margins to only 31% maintaining that view within two years.
Law firm leaders are beginning to understand what investors in legal AI startups have wagered: that a trillion-dollar industry built on information asymmetry and time-based billing faces fundamental restructuring. Whether that restructuring enriches legal AI platforms, their law firm customers, or both remains the central wager of the “platform war” now valued at $6.8 billion between Harvey and Legora alone.
In Part 1, I questioned whether legal AI valuations were visionary or delusional. Legora’s 10x ARR growth suggests genuine adoption - but most revenue remains untested by renewal cycles.
In Part 2, I argued firms were wheeling Trojan Horses through their gates. The Clifford Chance cuts validate this: the efficiency is real, the headcount implications are emerging, and clients are learning that legal work is more commoditised than premium rates suggested.
In Part 3, I warned that the real threat wasn’t Harvey but Accenture. The mega-merger wave confirms this: firms are consolidating not to compete with legal AI platforms but to survive the broader market restructuring where Big Four consultants capture client relationships through outcome-based AI services.
In Part 4, I urged firms to choose between renting and owning their AI capabilities. The merger announcements - all explicitly citing AI investment as strategic rationale - suggest most firms have chosen scale over sovereignty.
The developments of late 2024 and 2025 do not contradict the Trojan Horse thesis. They validate it. Law firms are simultaneously funding legal AI platforms at unprecedented valuations whilst merging defensively to survive the commoditisation those platforms accelerate. The $6.8 billion in combined Harvey-Legora valuations and the $8 billion in merger activity represent two sides of the same market restructuring: platforms capturing venture capital by demonstrating that legal work can be automated, and law firms seeking scale to survive clients’ recognition of precisely that fact.
The Trojan Horse has been wheeled through the gates. The question is whether the $8 billion merger wave represents law firms building higher walls - or merely rearranging the furniture whilst the gates remain open. Disruption will occur, the uncertainty is how quickly - and at whose expense? My money is on somebody other than the lawyers.